That’s the real answer to Wise vs Revolut. They overlap, but each is cheaper at different jobs. Wise is built for moving and receiving money across borders at the mid-market rate. Revolut is built for spending and everyday banking, with cheaper card use on weekdays and paid plans that remove most limits. Where you live changes the picture too, from deposit protection in the UK to who can sign up at all in Pakistan.
Wise is usually better for international transfers and getting paid from abroad. It uses the mid-market rate with a clear fee and gives you local account details in several currencies. Revolut is usually better for spending, travel and everyday banking, especially on a paid plan. Revolut’s free plan adds exchange fees on weekends and above a monthly limit.
Table of Contents
Wise vs Revolut at a Glance
In any Revolut vs Wise comparison, start here. Both offer multi-currency accounts, debit cards and international transfers, but they make money differently. Wise charges a small, upfront fee on each conversion and uses the mid-market exchange rate. Revolut offers free and paid plans, with fee-free exchange up to a limit on the free plan and fewer limits on paid ones.
| Feature | Wise | Revolut |
|---|---|---|
| Monthly fee | None | Free Standard plan, plus paid plans (UK: Plus £3.99, Premium £8.99, Metal £16.99, Ultra £60) |
| Exchange rate | Mid-market rate plus a fee shown upfront | Fee-free on weekdays up to a monthly limit on the free plan (£1,000 in the UK), then a fair-usage fee |
| Weekend exchange | No weekend markup | 1% on Standard, 0.5% on Plus, none on Premium and above |
| Free ATM cash (UK) | Up to £250 a month, then 2.69% on the amount above | Up to £200 a month across 5 withdrawals on Standard, then 2% |
| Physical card (UK) | £7 one-off | Free on some plans, delivery fee on others |
| Local account details | GBP, EUR, USD, AUD, CAD and more | Local GBP details and EU IBANs for euros |
| Is it a bank? | No, an e-money and payments provider | Yes in the UK, EU and Australia. Partner banks in the US |
| Best for | Sending and receiving money abroad | Spending, travel and everyday banking |
The Short Verdict
- Choose Wise if you get paid by clients abroad, send money home, or move larger amounts between currencies.
- Choose Revolut if you want one app for daily spending, budgeting, savings and travel, and you mostly exchange on weekdays.
- Use both if you travel and earn in other currencies. That’s what Danny does.
Wise vs Revolut Fees and Exchange Rates
Wise converts at the mid-market rate, the one you see on Google, and adds a separate conversion fee that it shows before you confirm. Revolut converts at its own rate, which is close to mid-market on weekdays. On the free plan, Revolut adds fees at weekends and once you pass a monthly exchange limit.
Revolut’s Weekend Markup and Monthly Limit
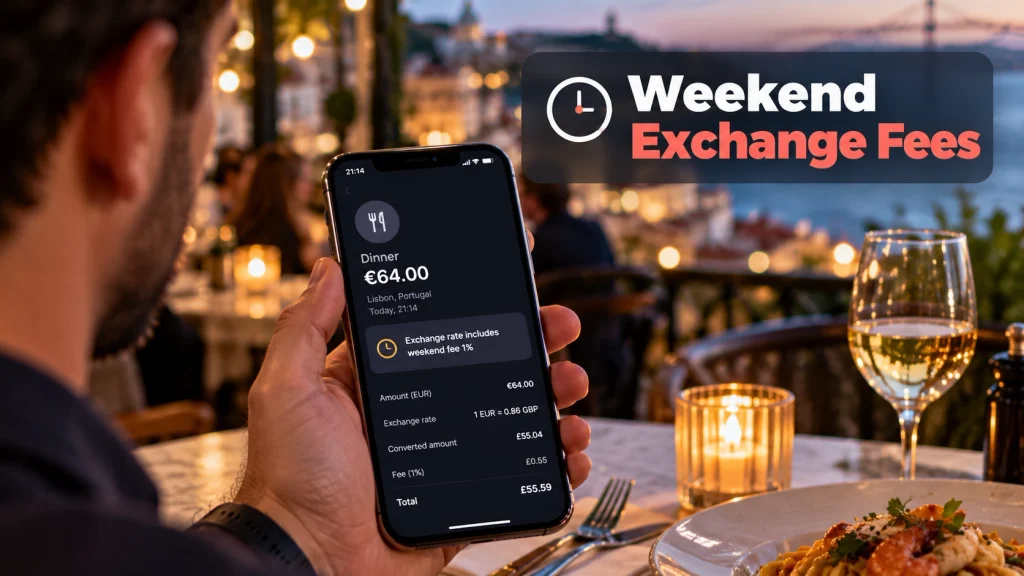
From 5pm Friday to 6pm Sunday, New York time, Revolut adds 1% to currency exchanges on the Standard plan and 0.5% on Plus. Premium, Metal and Ultra pay no weekend fee. On top of that, the UK Standard plan exchanges up to £1,000 a month without a fair-usage fee. Exchange more and a fee applies to the extra.
What the Weekend Fee Really Costs
On Danny’s Saturday in Lisbon, he spent about €500 including the cash withdrawal. A 1% markup added roughly €5. That’s small for one weekend. It adds up if you shop online in other currencies every weekend, or move savings between currencies on a Saturday. Simple fix: exchange on a weekday, or hold the currency in advance.
How Wise Shows Its Fee
Wise’s fee depends on the currencies and the amount, and drops for larger conversions. Its own US comparison quotes transfer fees starting at 0.41%. The fee appears as a separate line before you pay, so you can compare it with any bank’s rate in seconds. There’s no weekend change and no monthly allowance to track.
Sending Money Abroad: Wise vs Revolut
For sending money abroad, Wise usually wins on larger amounts and rarer currencies, because the mid-market rate and a percentage fee scale well. Revolut is often cheaper for small transfers, free between Revolut users, and convenient if you already hold the currency. Both pay euros out through SEPA and pounds through Faster Payments.
| Transfer type | Usually cheaper | Why |
|---|---|---|
| To another user of the same app | Revolut | Free and instant between Revolut users |
| Small amount, weekday, common currency | Either, check both | Revolut’s weekday rate is close to mid-market. Wise’s fee is small on small amounts |
| Large amount, for example £10,000 or more | Wise | Mid-market rate with volume discounts, no fair-usage fee |
| Weekend transfer on a free plan | Wise | No weekend markup |
| Less common currencies | Wise | Pays out in local currency to more countries |
Sending Euros by SEPA
Both apps pay euros into European IBANs through the SEPA system, often instantly. That’s what turns a slow, costly wire into a next-day or ten-second payment. Our step-by-step guide on how to make a SEPA payment shows what to enter, and SEPA Instant Payments explains why some still arrive the next day.
Getting Paid From Abroad: Wise vs Revolut
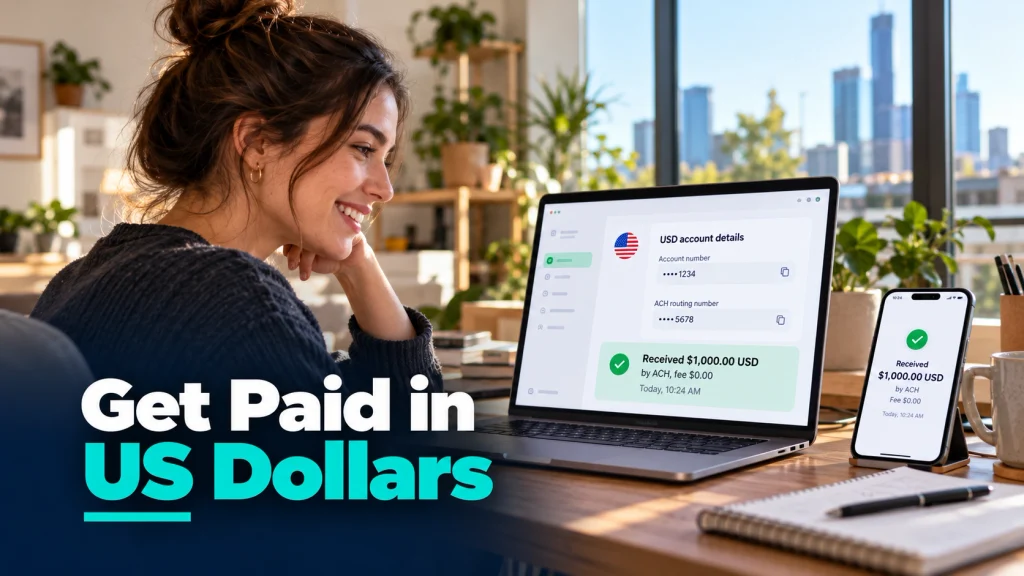
Wise is the stronger choice for getting paid by clients abroad. It gives you local account details in several currencies, including US dollar details that accept ACH payments for free. Revolut gives UK customers local pound details and EU IBANs for euros, which suits payments from the UK and Europe.
| Your client pays in | Wise | Revolut (UK customer) |
|---|---|---|
| US dollars by ACH | Free into USD details | No local US details for most UK customers. Payment arrives by SWIFT |
| US dollars by wire or SWIFT | $6.11 per incoming wire, plus any correspondent fees | By SWIFT, fees vary |
| Euros by SEPA | Euro IBAN | Euro IBAN |
| Pounds | Local sort code and account number | Local sort code and account number |
| Australian dollars | Local AUD details | Not for UK customers |
A client paying by SWIFT needs your IBAN or account number plus a SWIFT code. Our guides explain what a SWIFT code is and what an IBAN is. Local details avoid most of the correspondent fees that make wires arrive short.
Wise Card vs Revolut Card for Travel
For travel spending, Revolut is usually cheaper on weekdays and on paid plans, and it allows more free ATM withdrawals by number. Wise is steadier, with the same rate every day and a higher free cash limit in the UK. Both cards work in Apple Pay and Google Pay and let you freeze the card in the app.
ATM Withdrawals Compared
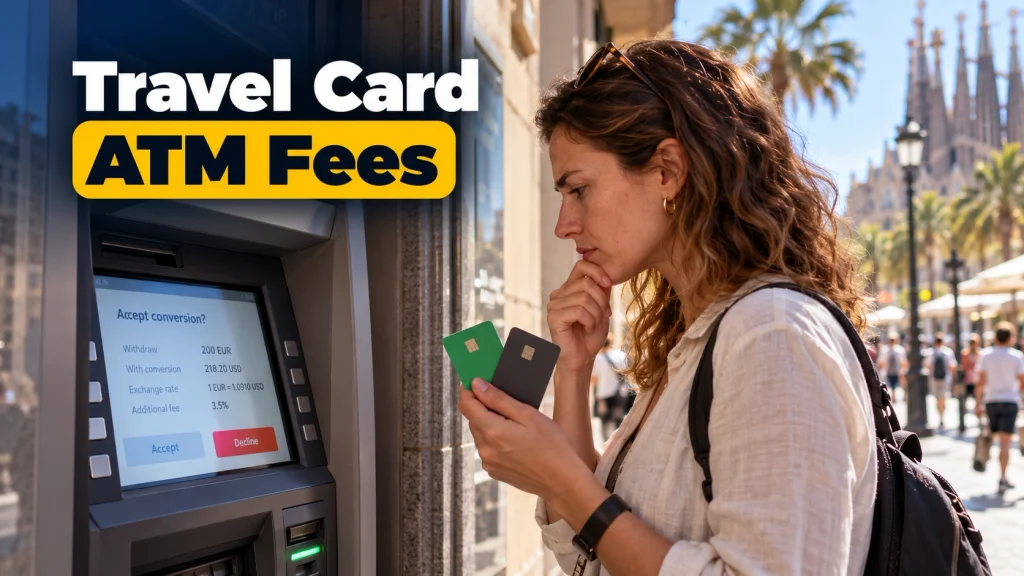
In the UK, Wise lets you withdraw up to £250 a month free, then charges 2.69% on the amount above that. Revolut’s Standard plan gives up to £200 a month across five withdrawals, then 2%. Paid Revolut plans raise the allowance. The ATM owner can still add its own charge on either card, so decline any offer to convert at the machine.
Wise vs Revolut in Australia and the US
Both apps work in Australia and the US, with local fees in local currency. Australian consumer group CHOICE found Revolut cheaper for spending abroad and small transfers, and Wise better for large transfers. In the US, Revolut’s paid plans are Premium and Metal, and the free plan has a monthly exchange allowance before a fee applies.
Is Your Money Safe With Wise or Revolut?
Revolut is now a licensed bank in the UK, the EU and Australia, so eligible deposits there are covered by government deposit protection. Wise is not a bank. It holds customer money as an e-money and payments provider, which means safeguarding in segregated accounts, not deposit insurance. Both are regulated in every market they serve.
| Market | Revolut | Wise |
|---|---|---|
| United Kingdom | Full UK banking licence after leaving mobilisation in March 2026. Eligible deposits covered by the FSCS up to £120,000 | E-money institution. Money safeguarded, not covered by the FSCS |
| European Union | Revolut Bank UAB, licensed in Lithuania. Eligible deposits covered up to €100,000 | E-money institution. Money safeguarded |
| Australia | Licensed bank since 22 July 2026. Eligible AUD deposits covered up to AU$250,000 | Regulated payments provider, not a bank |
| United States | Not a bank. Balances held at partner banks with FDIC cover up to $250,000 per bank | Licensed money transmitter, not a bank. Standard balances are not FDIC insured |
Frozen Accounts and Support
Both apps can freeze an account during a compliance review, and complaints about this are common on Reddit and Trustpilot for each. It usually happens after an unusual incoming payment. Keep invoices for client payments, answer document requests quickly, and don’t keep every penny in one app.
Wise vs Revolut: Which Is Better in Your Country?
Which is better depends partly on where you live. In the UK, the EU and Australia, both apps are open to residents and Revolut is a bank. In the US, both work but Revolut runs through partner banks. In Pakistan, neither app opens accounts for residents, so freelancers there need other routes.
| Where you live | Wise | Revolut | Our pick |
|---|---|---|---|
| United Kingdom | Available | Available, UK bank | Revolut for spending, Wise for getting paid in dollars |
| Europe (EEA) | Available | Available, EU bank | Revolut for daily banking, Wise for transfers outside Europe |
| Australia | Available | Available, Australian bank | Revolut for travel, Wise for large transfers |
| United States | Available in most states | Available | Wise for receiving and sending abroad, Revolut for travel spending |
| Pakistan | Not open to residents | Not open to residents | Payoneer or a bank account, see below |
Wise and Revolut in Pakistan
Wise’s own Pakistan guide says residents can’t sign up for Wise accounts, and Revolut doesn’t offer accounts to Pakistani residents either. Clients abroad can still send money to a Pakistani bank through Wise. For receiving in your own name, most Pakistani freelancers use Payoneer, covered in how to receive money with Payoneer.
Wise vs Revolut: Four Real Costs Compared
The cheaper app changes with the job. These four everyday cases, using UK customers on free plans, show where each one wins. Fees are rounded and based on published UK pricing in October 2026. Your app always shows the exact cost before you confirm, so check it each time.
| Scenario | Wise | Revolut Standard | Cheaper |
|---|---|---|---|
| Spend €500 by card on a Saturday | Mid-market rate plus Wise’s small conversion fee | Revolut rate plus 1% weekend markup, about €5 | Usually Wise at weekends, Revolut on weekdays |
| Withdraw €250 cash abroad | Free, inside the £250 monthly limit | The part above the £200 free limit is charged at 2% | Wise |
| Receive a $1,000 invoice from a US client | Free by ACH into USD details | Arrives by SWIFT, with possible correspondent fees | Wise |
| Send £50 to a friend who also uses the app | Small fee if a conversion is needed | Free between Revolut users | Revolut |
Can You Use Wise and Revolut Together?
Yes, and many freelancers and travellers do. Use Wise as your receiving and transfer account, with local details for client payments. Use Revolut as your spending card and daily account. Moving money between them is a normal bank transfer, free in pounds and euros through Faster Payments or SEPA in most cases.
Danny’s Two-App Setup
- Clients in the US and Europe pay into his Wise dollar and euro details.
- He converts to pounds in Wise on a weekday, at the mid-market rate.
- Before a trip, he tops up Revolut and exchanges into the travel currency on a Thursday.
- He spends with the Revolut card and keeps Wise as a backup card.
If you also take card payments online, check whether you can transfer Stripe to Payoneer. The remote developer tax and banking checklist covers record-keeping for income from abroad.
Frequently Asked Questions
Short answers to the Wise vs Revolut questions people ask most.
Is Wise cheaper than Revolut?
For international transfers, weekend exchanges and receiving money from abroad, Wise is usually cheaper. For weekday card spending within your free allowance, transfers to other Revolut users and small amounts, Revolut is often cheaper. On a paid Revolut plan, weekend and limit fees disappear, but you pay a monthly fee. Compare the final amount in both apps before any large transfer.
Which is better for travel, Wise or Revolut?
Revolut is usually better for travel if you spend on weekdays or have a paid plan. Its weekday rate is sharp, and it allows more free ATM withdrawals by count. Wise is better if you often spend at weekends, withdraw larger amounts of cash or want the same rate every day. Many travellers carry both cards, so one can back up the other if a card is lost.
Is Revolut a bank?
Yes, in the UK, the EU and Australia. Revolut left the UK mobilisation stage with a full banking licence in March 2026. It runs Revolut Bank UAB in the EU, and became a licensed bank in Australia on 22 July 2026. In the US, Revolut is not a bank and holds balances at partner banks. Wise is not a bank anywhere.
Is my money protected with Wise?
Wise safeguards customer money, which means it keeps it separate from its own funds in accounts at large banks or in low-risk assets. If Wise failed, safeguarded money should be returned to customers, minus administration costs. That’s different from deposit insurance such as the UK’s FSCS, which Wise balances don’t have. For large savings, a protected bank account is safer.
Can I use Wise or Revolut in Pakistan?
Not as a resident. Neither Wise nor Revolut opens accounts for people living in Pakistan. Visitors can use cards from their home country while travelling there, and senders abroad can use Wise to pay into a Pakistani bank account in rupees. Pakistani freelancers who need dollar or euro account details usually use Payoneer or receive bank transfers by SWIFT.
Which is better for freelancers, Wise or Revolut?
Wise, for most freelancers paid from abroad. Its local account details in dollars, euros, pounds and Australian dollars let clients pay you as a domestic transfer, and incoming US ACH payments are free. Revolut Business suits freelancers who mainly invoice UK and European clients and want spending tools, team cards and expense tracking in the same app.
Does Revolut charge on weekends?
Yes, on its cheaper plans. From 5pm Friday to 6pm Sunday, New York time, Revolut adds 1% to currency exchanges on the Standard plan and 0.5% on Plus. Premium, Metal and Ultra have no weekend markup. The fee applies to card payments and exchanges in a foreign currency, not to spending in your own currency.
Can I send money from Revolut to Wise?
Yes. Add your Wise account details as a payee in Revolut and send a normal bank transfer. Pounds go by Faster Payments and euros by SEPA, usually free and fast. Sending in a currency neither account holds locally may go by SWIFT, which costs more. The same works in reverse, from Wise to your Revolut account details.
Which has the better debit card?
It depends on how you use it. Revolut’s card offers more free ATM withdrawals by count, spending controls, disposable virtual cards and plan perks such as travel insurance on higher tiers. Wise’s card offers the mid-market rate every day, a higher free cash amount in the UK and automatic conversion from whichever balance is cheapest. Both support Apple Pay and Google Pay.
Which is better for large transfers?
Wise, in most cases. Its fee drops as the amount grows, it uses the mid-market rate, and there’s no fair-usage limit to cross. On Revolut’s free plan, a large exchange can pass the monthly allowance and attract a fee. For very large amounts, compare the final received amount in both apps and with your bank, and send on a weekday.
Pick by the Job, Not the Brand
Danny’s Lisbon weekend cost him about €5 more than it needed to, which is hardly a disaster. But it explained why both apps stay on his phone. Wise collects his client payments in dollars and euros for free or close to it. Revolut pays for his coffee and trams, and he now exchanges his travel money on a Thursday instead of a Saturday.
That’s the honest Wise vs Revolut answer. Wise wins on moving and receiving money across borders, with one clear fee and the real exchange rate. Revolut wins on spending, everyday banking and, in the UK, EU and Australia, deposit protection as a licensed bank. In Pakistan, neither is open to residents, so Payoneer and local banks fill the gap. Run the four cost examples against your own month, keep the cheaper app for each job, and the fees mostly disappear. Which job does your money app actually do most often?