What you cannot do is ask the buyer to send the money as Friends and Family. PayPal’s User Agreement prohibits it in exactly those words, and the penalty is losing the ability to receive friends-and-family payments at all. Almost every article on this topic leads with that tip. It is the one move that can cost you the account.
This guide covers what you actually pay in 2026, which reductions are real, the break-even math on micropayments, whether you can pass the fee to the customer, and what the tax rules say now that the $600 threshold everyone remembers is gone.
Table of Contents
What You Actually Pay to Receive Money in 2026
Receiving money for goods and services costs 2.99% + $0.49 on a standard commercial transaction in the US, or 3.49% + $0.49 through PayPal Checkout and invoicing. Receiving a personal transfer from someone’s PayPal balance or bank account is free. International payments add about 1.5%, and currency conversion adds a 3% to 4% spread on top of everything else.
| Transaction type | US rate | Fixed fee |
|---|---|---|
| Commercial transaction, standard | 2.99% | $0.49 |
| PayPal Checkout | 3.49% | $0.49 |
| Invoicing | 3.49% | $0.49 |
| Micropayments, if approved | 4.99% | $0.09 |
| QR code, in person | 2.29% | $0.09 |
| Confirmed charity | 1.99% | $0.49 |
| Personal transfer, funded by balance or bank | No fee | None |
| Personal transfer, funded by card | 2.90% | Fixed fee applies |
| International surcharge | Add about 1.5% | Varies by region |
| Currency conversion | 3% to 4% spread | Built into the rate |
| Instant Transfer to bank or debit | 1.75% | Min $0.25, max $25.00 |
Rates from PayPal’s published US fee pages and the PayPal User Agreement, checked October 2026. Rates differ outside the US.
Two line items deserve a second look. The currency conversion spread is the fee people never notice, because it is baked into the exchange rate rather than shown as a charge. On a $2,000 international invoice, a 4% spread is $80 that never appears as a fee on your statement. And Instant Transfer caps at $25, which means on a $5,000 withdrawal you pay $25 to receive money two days sooner than the free standard transfer.
The Advice That Can Cost You Your Account
Here is the clause, quoted directly from PayPal’s US User Agreement. Sellers must:
“Not ask your buyer to send you money as a personal transaction (often referred to as using the ‘Send Money to a Friend or Family Member’ feature).”
And the buyer side:
“You must not send money as a personal transaction (often referred to as using the ‘Send Money to a Friend or Family Member’ feature in your PayPal account) when you are paying for goods or services.”
The consequence PayPal states: “If you do so, PayPal may remove your PayPal account’s ability to accept payments from friends or family members.”
So the tactic is prohibited on both sides, in writing, and the penalty lands on the seller. That is the first reason to drop it.
The second reason is more immediate. Personal transactions carry no Seller Protection. A buyer who pays as Friends and Family can still dispute the charge through their bank or card issuer, and you have no PayPal protection to fall back on, because PayPal’s Seller Protection applies to goods-and-services transactions. You saved $3.48 on a $100 sale and gave up your defence on the whole $100.
The third reason is the buyer’s. Friends-and-family payments have no PayPal Purchase Protection either. Any buyer who knows this will refuse, and a seller asking for it is a recognised scam signal. Asking damages the sale more often than it saves the fee.
There is no version of this that works. Not calling it a “gift,” not splitting the payment, not asking politely. The clause does not care how it is phrased.
Can You Make the Customer Pay the Fee?
Not as a surcharge. PayPal’s User Agreement is direct:
“You agree that you will not impose a surcharge or any other fee for accepting PayPal as a payment method.”
A handling fee is treated differently, but only under a strict condition: it cannot function as a surcharge, and it cannot exceed what you charge on non-PayPal transactions. So a flat $5 handling charge applied to every order regardless of payment method is defensible. A “3% PayPal fee” line that appears only when someone pays with PayPal is the thing the clause prohibits.
What works instead is pricing. Build your processing cost into the rate you quote and the fee stops being a separate conversation. A freelancer who charges $515 instead of $500 and absorbs the fee is doing the same arithmetic as one who adds a surcharge, without breaching the agreement or giving the client a line item to argue about.
If the fee is landing on a WooCommerce store rather than an invoice, the gateway you choose decides which rate applies, and adding PayPal to WooCommerce walks through the current integration rather than the retired ones.
For invoiced work, there is a cleaner route: offer a small discount for bank transfer or ACH. A 2% early-payment or direct-transfer discount is a legitimate incentive, it is not conditioned on avoiding a specific payment brand, and it moves large invoices off card rails entirely.
Micropayments: The Only Rate Switch With Real Math Behind It
PayPal’s micropayments rate is 4.99% + $0.09 instead of 2.99% + $0.49. The percentage is higher and the fixed fee is much lower, so it wins on small transactions and loses on large ones. The crossover is exactly $20 against the standard rate.
| Payment | Standard, 2.99% + $0.49 | Micropayments, 4.99% + $0.09 | Cheaper |
|---|---|---|---|
| $3 | $0.58 (19.3%) | $0.24 (8.0%) | Micropayments |
| $5 | $0.64 (12.8%) | $0.34 (6.8%) | Micropayments |
| $10 | $0.79 (7.9%) | $0.59 (5.9%) | Micropayments |
| $15 | $0.94 (6.3%) | $0.84 (5.6%) | Micropayments |
| $20 | $1.09 | $1.09 | Identical |
| $25 | $1.24 (5.0%) | $1.34 (5.4%) | Standard |
| $50 | $1.98 (4.0%) | $2.58 (5.2%) | Standard |
| $100 | $3.48 (3.5%) | $5.08 (5.1%) | Standard |
Against the 3.49% + $0.49 Checkout rate, the crossover moves to about $26.67.
Read the $3 row again. A $3 payment on the standard rate loses 19.3% to fees. On micropayments it loses 8%. If you sell digital downloads, single articles, tips, in-app items, or print-on-demand singles, this is the largest fee reduction available to you and it requires no change to how you sell.
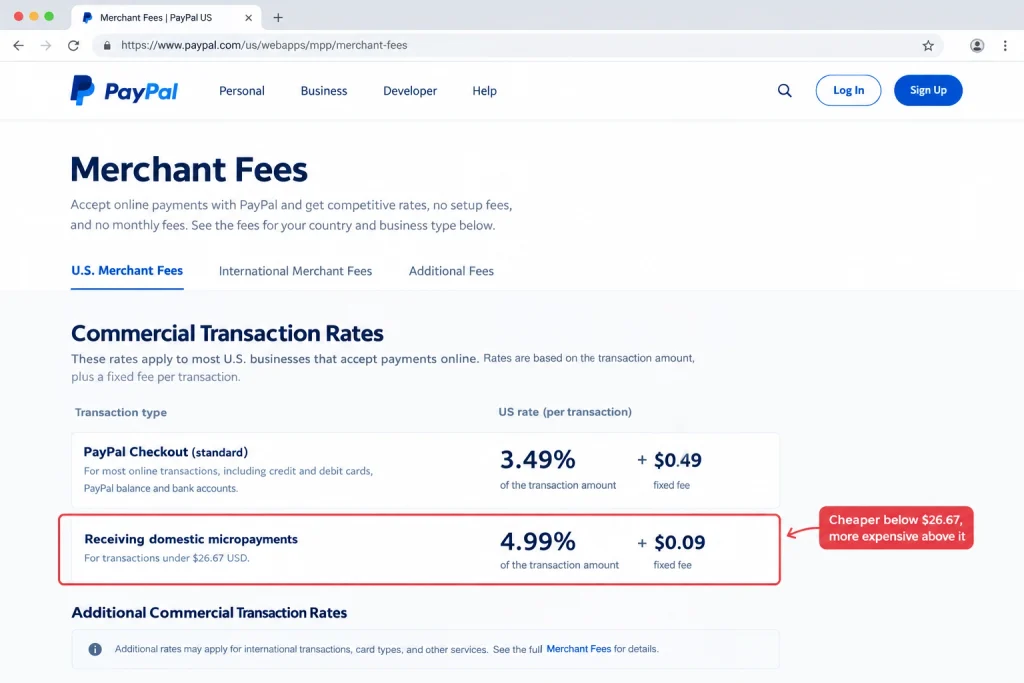
The catch is that micropayments is not a setting. You apply for it, and PayPal applies it at the account level, not per transaction. So an account on micropayments pricing pays 4.99% + $0.09 on everything, including a $400 sale where that rate is clearly worse. If your order values straddle $20, the usual answer is two business accounts: one on micropayments for the low-value products, one on standard pricing for everything else.
The Reductions That Are Actually Available
Confirmed charity rate, 1.99% + $0.49. If you run a registered 501(c)(3), confirming your charity status with PayPal drops you from 2.99% to 1.99%. On $10,000 a month in donations that is $100 a month. Many small nonprofits never complete the confirmation and pay the commercial rate for years.
QR code payments, 2.29% + $0.09. The cheapest rate PayPal offers for in-person sales. Market stalls, pop-ups, service calls, and any transaction where the customer is physically present should be taking QR payments rather than a card reader on a higher rate.
Volume discounts above $3,000 a month. PayPal publishes tiered merchant rates for higher processing volumes, with the better tiers at much higher thresholds. This is not automatic. You ask. If you are consistently above $3,000 a month and have never contacted PayPal about rate tiers, you are paying list price by default.
Standard bank withdrawal instead of Instant Transfer. Standard transfer to a linked bank account is free and takes one to three business days. Instant Transfer costs 1.75%, capped at $25. A business withdrawing $8,000 a month in two Instant Transfers burns $50 a month, or $600 a year, to move money a day or two earlier. If you have never linked a bank account because you do not have one on file, verifying PayPal without a bank account covers the alternatives.
Hold foreign currency instead of converting. If you regularly receive euros or pounds, open a balance in that currency and keep it there. PayPal converts automatically by default, charging the 3% to 4% spread on every payment. Holding the currency means you convert once, when the rate suits you, or spend it directly. On $50,000 a year of euro income, this single change is worth $1,500 to $2,000.
Invoice in the client’s currency where you can bill locally. Cross-border adds about 1.5% on top of conversion. A client who can pay a local account avoids the cross-border surcharge entirely.
Consolidate small invoices. Every transaction carries the $0.49 fixed fee. Twenty $25 invoices in a month cost $9.80 in fixed fees alone. One $500 invoice costs $0.49. For retainer clients, monthly billing instead of per-task billing is free money.
Review your dispute rate. A chargeback costs $20 on top of the lost sale, and PayPal’s dispute fees run $15 for standard volume and $30 for high dispute rates. Sellers with a dispute problem often pay more in dispute fees than they would save from any rate change. Clear product descriptions and fast shipping beat every pricing trick here, and the protections each processor actually gives you are worth comparing: see how Stripe and PayPal handle seller and buyer safety.
Where PayPal Stops Being the Right Tool
Honest answer: above a certain volume, PayPal is not the cheapest way to get paid, and fee optimisation inside PayPal stops being the question.
| Situation | Better fit | Why |
|---|---|---|
| Large international invoices | Wise Business, Payoneer | Conversion spreads well under PayPal’s 3% to 4% |
| High-volume online store | Stripe, or a negotiated acquirer rate | Lower effective rate at scale, better dispute tooling. The full numbers are in our Stripe and PayPal fee comparison |
| Domestic B2B invoices | ACH or bank transfer | Flat fee or free, no percentage |
| Buyers who insist on PayPal | PayPal | Checkout conversion is worth the fee |
That last row matters more than the first three. PayPal’s fee buys you a payment method a large share of buyers already trust and have saved. Moving a store off PayPal to save 1% and losing 3% of conversions is a loss, not a saving. Measure before you switch.
Tax: The $600 Threshold Everyone Remembers Is Gone
PayPal issues a Form 1099-K when you receive more than $20,000 and more than 200 transactions for goods and services in a calendar year. The One Big Beautiful Bill Act, signed in 2025, restored that original federal threshold. The $600 figure that circulated for years was repeatedly delayed and never took effect federally.
Several states set their own, much lower thresholds:
| State | Threshold |
|---|---|
| Maryland, Massachusetts, Vermont, Virginia | $600 |
| Illinois | Over $1,000 and four or more transactions |
Two points that a lot of fee-avoidance advice gets dangerously wrong.
A 1099-K is a reporting form, not the definition of taxable income. Business income is reportable whether or not a form is issued. Receiving $8,000 through PayPal and getting no 1099-K does not make that $8,000 untaxed. Advice that frames fee avoidance as a way to stay under a reporting threshold is describing unreported income, and that is a different problem from a 2.99% fee.
PayPal fees are a deductible business expense. The fees you do pay reduce your taxable income. On $60,000 of PayPal revenue at 2.99% + $0.49 per transaction, you are deducting roughly $2,000 in processing costs. Worth recording properly rather than estimating, and the fee column is already there in your statements: here is how to download your PayPal transaction history in a format an accountant can work from.
Tax rules vary by country and by state, and this is general information rather than tax advice. A one-off conversation with an accountant costs less than most people’s annual PayPal fees.
What Does Not Work
| Tactic | Why it fails |
|---|---|
| Asking buyers to pay as Friends and Family | Prohibited by the User Agreement for both parties; risks losing F&F access; voids Seller Protection |
| Adding a “PayPal fee” line to the invoice | Surcharging is prohibited; a handling fee must apply regardless of payment method |
| Marking business payments as “gifts” | Same clause, different wording. The transaction type is what matters |
| Splitting one payment into several | Each one carries the $0.49 fixed fee; this increases total cost |
| Using a Personal account for business income | Does not change the rate on goods-and-services payments and can trigger a limitation |
| Refunding and re-taking payment another way | The fixed fee is not returned on refunds |
| Waiting for PayPal to offer you a better rate | Volume tiers are requested, not granted automatically |
What to Do This Week
- Check your average transaction value. Under $20, apply for micropayments. The $3 and $5 rows in the table above are where the real money is.
- If you are a registered nonprofit, confirm your charity status and drop to 1.99%.
- If you are above $3,000 a month, contact PayPal and ask about volume rate tiers. Nobody will offer.
- Turn off Instant Transfer as a habit. Use standard withdrawal unless you genuinely need the money today.
- If you receive foreign currency, open a balance in that currency and stop auto-converting.
- Consolidate recurring small invoices into monthly billing.
- Stop asking anyone to pay as Friends and Family, and if a seller asks you to, that is a reason to walk away.
Frequently Asked Questions
Does the sender or the receiver pay PayPal fees?
On a goods-and-services payment, the receiver pays. The fee is deducted from the amount before it lands in your balance, so a $100 sale arrives as $96.52 at the standard 2.99% + $0.49. On a personal transfer funded by a balance or bank account, nobody pays. On a personal transfer funded by a card, the sender pays 2.90% plus a fixed fee.
Can I receive money on PayPal with no fee at all?
Yes, but only for genuine personal transfers funded by a PayPal balance or bank account. Splitting a dinner bill, repaying a friend, or receiving a gift costs nothing. Any payment for goods or services carries a fee, and there is no legitimate way around that.
Is it illegal to use Friends and Family for business payments?
It is not a criminal matter, but it breaches PayPal’s User Agreement, which prohibits both asking for it and sending it that way. PayPal can remove your account’s ability to accept friends-and-family payments. It also voids Seller Protection and the buyer’s Purchase Protection, which is the practical risk.
How do I avoid PayPal currency conversion fees?
Open a balance in the currency you receive and keep the funds in it rather than letting PayPal convert automatically. You can then convert at a moment you choose, spend the currency directly, or withdraw to an account in that currency. For large volumes, a multi-currency account with Wise or Payoneer typically converts at a narrower spread than PayPal’s 3% to 4%.
Can I pass the PayPal fee on to my customer?
Not as a PayPal-specific surcharge. The User Agreement prohibits imposing a surcharge for accepting PayPal. A handling fee is permitted only if it applies regardless of payment method and does not exceed what you charge on other methods. Building the cost into your prices, or offering a discount for bank transfer, achieves the same result without breaching the agreement.
What is the cheapest way to receive money on PayPal?
For in-person sales, QR code payments at 2.29% + $0.09. For registered nonprofits, the confirmed charity rate at 1.99% + $0.49. For transactions under $20, micropayments at 4.99% + $0.09. For everything else, the standard 2.99% + $0.49 commercial rate is the floor without a negotiated volume tier.
Do I need a Business account to receive payments?
No, a Personal account can receive goods-and-services payments, but it will pay the same commercial rate and it lacks invoicing, multi-user access, and reporting. Running consistent business income through a Personal account is also a common trigger for account review. If you are selling, use a Business account.
How much does PayPal charge on $1,000?
At the standard commercial rate of 2.99% + $0.49, a $1,000 domestic payment costs $30.39, leaving $969.61. Through PayPal Checkout at 3.49% + $0.49, it costs $35.39. An international payment adds roughly 1.5%, and if currency conversion is involved, a further 3% to 4% spread applies on top.
Will I get a 1099-K from PayPal?
Only if you receive more than $20,000 and more than 200 goods-and-services transactions in a calendar year, following the restoration of that federal threshold in 2025. Maryland, Massachusetts, Vermont, and Virginia set a $600 threshold, and Illinois uses over $1,000 with four or more transactions. Income is reportable regardless of whether a form arrives.
Are PayPal fees tax deductible?
Yes, for business income. Payment processing fees are an ordinary business expense and reduce your taxable profit. Export your transaction history and record the fee column rather than estimating it, since the fixed fees add up to more than most people expect across a year of small transactions.
Does PayPal refund fees when I refund a customer?
The percentage portion is returned, but the fixed fee is not. On a refunded $50 sale at 2.99% + $0.49, you keep the $1.50 back and lose the $0.49. A high refund rate therefore carries a cost that no rate change addresses.
Is there a monthly limit on fee-free personal transfers?
There is no published fee-free cap on personal transfers funded by a balance or bank account, but accounts receiving unusually high volumes of personal transfers do attract review, because that pattern is what business payments disguised as personal transfers look like. Receiving business income this way is the risk, not the volume itself.
The Bottom Line
The honest answer to “how do I avoid PayPal fees when receiving money” is that you reduce them rather than avoid them, and the reductions are unglamorous: apply for micropayments if your payments are small, confirm charity status if you qualify, ask for a volume tier if you are above $3,000 a month, stop paying for Instant Transfer, and hold foreign currency rather than converting it on arrival.
The move to delete from your playbook is asking anyone to pay as Friends and Family. PayPal prohibits it in the agreement you accepted, it voids your Seller Protection, and it reads to any experienced buyer as a warning sign. The $3.48 you save on a $100 sale is not worth the exposure.
If your fees have become a real line item rather than an annoyance, the question is usually not how to shave PayPal down but whether PayPal should still be carrying that payment volume at all. Webzeto’s eCommerce development team sets up payment stacks that route each payment type through the cheapest rail it qualifies for.
Sources: PayPal User Agreement, PayPal consumer fees, Will PayPal report my sales to the IRS?. All checked October 2026.